Savaspin Withdrawals: Process, KYC and What to Check
 Available in GB
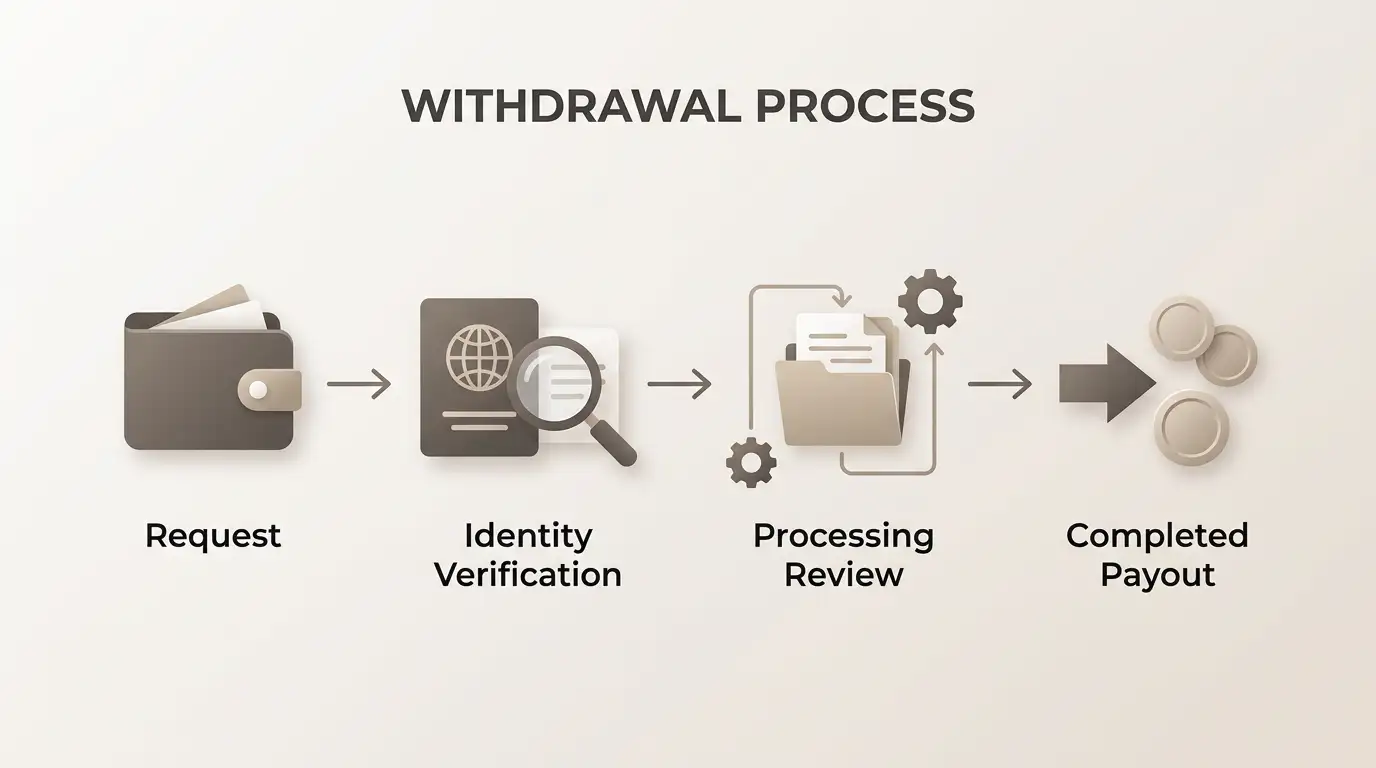
Savaspin withdrawals are tied closely to identity verification. The brand’s current KYC policy says it can restrict payments or withdrawals until identity is sufficiently established, and its terms say a first withdrawal can trigger verification. The practical sequence is therefore request, payment-method checks, KYC or account review where required, internal processing, and then transfer through the selected payout rail.
Savaspin’s general terms say withdrawal processing can take up to 72 hours before the payment method’s own settlement time is added. They also state that the current withdrawal limit is shown in the cashier and that identity checks can occur at first withdrawal and later. For UK residents, another clause is crucial: the United Kingdom is listed as a Restricted Country, and the terms warn that withdrawals or refunds cannot be guaranteed when that country restriction is breached.
Table of Contents
- The Savaspin withdrawal process in plain English
- Savaspin withdrawal terms at a glance
- Why KYC can delay a payout
- Method matching matters
- What the 72-hour processing term covers
- A practical pre-withdrawal checklist
- When to contact Savaspin support
- How to judge a withdrawal claim you see elsewhere
- What to do when a withdrawal status does not move
- Bottom line
The Savaspin withdrawal process in plain English
A payout begins in the cashier, but the payment request is only one part of the process. Savaspin’s public policies show that the operator can apply identity and transaction checks before funds are released. That is why a user who has deposited successfully should not assume that a withdrawal will be an automatic reversal of the deposit.
- Open the withdrawal area. Check which payout methods are actually offered to the account at that moment.
- Choose an eligible route. Savaspin’s general terms say withdrawals should be made back through the same method used for the deposit where the route supports it.
- Enter the requested amount. Read any live minimum, maximum or account-level limit shown before submission.
- Complete verification if requested. Savaspin’s KYC policy allows identity, address and payment-method documents to be requested according to risk and transaction context.
- Wait for internal review and release. The general terms currently state that withdrawal processing can take up to 72 hours before the payment method’s own transfer time is added.
- Escalate through support if needed. Savaspin advertises 24/7 live chat and also provides email support.
This process view is more useful than a single advertised speed because it tells you where a delay can occur and which part you can actually act on.
Savaspin withdrawal terms at a glance
| Question | Current term | How to use it |
|---|---|---|
| Is KYC part of withdrawals? | Yes. Savaspin’s KYC policy says withdrawals can be restricted until identity is sufficiently determined. | Expect verification to be a possible prerequisite, especially around a first withdrawal or higher-risk review. |
| Can documents be requested? | Yes. The policy lists identity, address and payment-method documents among the categories that can be requested depending on the check. | Keep account and payment details accurate and use the dedicated KYC guide for the document process. |
| Does Savaspin state an internal processing window? | Its current general terms say withdrawal processing can take up to 72 hours. | Treat this as a general platform term, not a guaranteed total time for every eligible account or payment method. |
| What withdrawal methods can an eligible account use? | They depend on the account and payment routes shown in the cashier. | Use the withdrawal screen to see the available route for an eligible account. |
| What withdrawal limit applies? | Limits can depend on payment method and loyalty level, and the current value is shown in the cashier. | Check the live amount field for an eligible account rather than relying on an old review. |
| Are there guaranteed withdrawal fees? | Fees can depend on the payment route; bank transfers can involve intermediary-bank charges under the general terms. | Read the live cashier and any payment-provider notice before submitting. |
Why KYC can delay a payout
Savaspin’s KYC policy uses a risk-based framework rather than describing one identical verification path for every customer. It refers to simplified, customer and enhanced due-diligence levels. The exact checks can therefore vary with the customer, transaction and risk profile.
The policy also says Savaspin can request information or documents it considers necessary to establish a user’s identity and location. Examples in the policy include a passport or ID card, proof of address and payment-method documents. It also explains that submitted documents can be approved, rejected or returned with a request for more information.
For a withdrawal page, the important point is not the complete document inventory. It is that verification can be a real operational dependency. If a user enters a different address from the one shown on supporting documents, uses unclear scans, or cannot show ownership of a payment method when asked, the payout can remain blocked while the review is unresolved.
The dedicated Savaspin KYC covers verification in more depth. Keeping that detail on its own page avoids turning this withdrawal guide into a duplicate document checklist.
Method matching matters
Savaspin’s general terms say withdrawals have to be made to the same method used for the deposit where applicable. This is a common anti-fraud and anti-money-laundering control because it reduces the chance that money enters through one source and exits through an unrelated destination.
That does not mean every deposit method will always support an identical withdrawal path. Some payment systems are one-way, some accounts can have method-specific restrictions, and the cashier can present different payout choices after login. The useful rule is therefore to check both deposit and withdrawal capability before funding, especially if quick access to a particular payout rail matters to you.
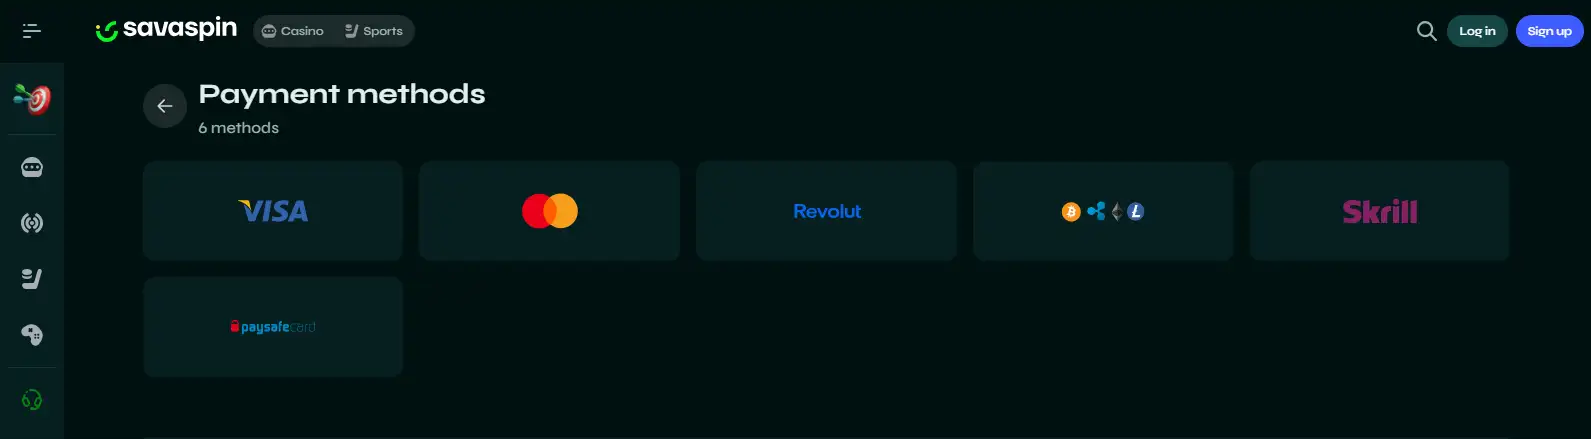
The broader method list is covered on the Savaspin payment methods page. That page explains the public platform payment categories and why the cashier is more authoritative than a static logo strip for account-specific availability.
What the 72-hour processing term covers
Savaspin’s current general terms state that withdrawal processing can take up to 72 hours and that, once a withdrawal has been processed and released, the payment method can add its own transfer time. This is useful because it separates internal processing from the external payment leg.
It still should not be read as a universal total-time promise. A request that triggers KYC, enhanced checks, a payment-method problem, an account mismatch or a request for more information can take a different path. Likewise, the receiving bank, wallet or card system can have its own settlement timing after Savaspin releases the payment.
The 72-hour figure covers Savaspin’s stated processing period, not necessarily the full time until funds arrive. After a withdrawal is released, the payment method can add its own settlement period. Identity checks, account review and method matching can also affect when a request reaches the release stage.
A practical pre-withdrawal checklist
- Confirm your account name, date of birth and address are accurate before requesting a payout.
- Check that the payment method belongs to you and that the details match the account information.
- Open the withdrawal cashier and record the methods and limits actually shown for your account.
- Read any live fee or processing notice before you submit.
- If KYC is requested, send clear and current documents through the official account process rather than by an unofficial channel.
- Keep the request reference and note the submission date and status changes.
- If the status stalls, contact support with the request reference rather than opening duplicate withdrawal requests.
Accurate account details, genuine documents and a payout method connected to the account can reduce avoidable delays. These steps are relevant to existing eligible accounts and do not override the country restrictions in Savaspin’s terms.
When to contact Savaspin support
Savaspin advertises 24/7 live chat and also provides email support. Support is the appropriate route when the cashier does not explain a status, a requested document has been submitted but the account has not updated, or the payment method shown at deposit is not available at withdrawal.
When escalating, provide the transaction or withdrawal reference, the approximate request time and the status currently shown. Avoid posting identity documents, card data or wallet credentials in public forums. If support asks for additional verification, use the official account or KYC channel specified by Savaspin.
Public review sites can be useful for seeing the kinds of issues users discuss, but an individual complaint cannot prove what happened to another account. The separate Savaspin reviews page treats user reports as anecdotal context rather than as established operational facts.
How to judge a withdrawal claim you see elsewhere
Savaspin separates internal processing from payment-method settlement. Its general terms allow up to 72 hours for the processing stage, while the time after release depends on the chosen method. Account limits can also vary and are shown in the cashier.
The withdrawal limit is not one fixed platform-wide number. Savaspin states that limits can depend on payment method and loyalty level and that the current amount appears in the Withdrawal section of the cashier. Bank-transfer charges can also arise through intermediary banks.
What to do when a withdrawal status does not move
A static status does not automatically mean that a payment has failed. The first step is to identify which stage the request has reached. If the account is waiting for documents, finish that task before asking support to chase the payment rail. If verification is complete but the request is still shown as pending, compare the elapsed time with the current terms and check whether the cashier displays a message about method-specific processing.
Avoid cancelling and resubmitting repeatedly unless support tells you to do so. Multiple requests can make it harder to follow the transaction history and can reset the point from which you are measuring progress. Keep saved copies of the status page, note when any requested documents were submitted, and retain support ticket numbers.
If a request is shown as processed or released but the money has not arrived, the relevant question changes from internal approval to payment settlement. At that stage, ask for the transaction reference that can be used with the bank, wallet or payment provider. This distinction helps support investigate the right part of the chain rather than treating every delay as the same problem.
Bottom line
Savaspin has a documented withdrawal and KYC framework, and its current general terms provide some platform-level detail, including a same-method principle and an internal processing window of up to 72 hours. The brand’s KYC policy also makes clear that payment or withdrawal can be restricted until identity is sufficiently determined.
For an eligible account, the safest way to turn those general rules into an account-specific answer is to check the live cashier for available payout methods, current limits and any displayed charges, then complete verification promptly if requested. United Kingdom residents are currently restricted from real-money deposits and play under Savaspin’s terms. For the wider product context, return to the full Savaspin review.
Published by the Sava Spin Casino team.